
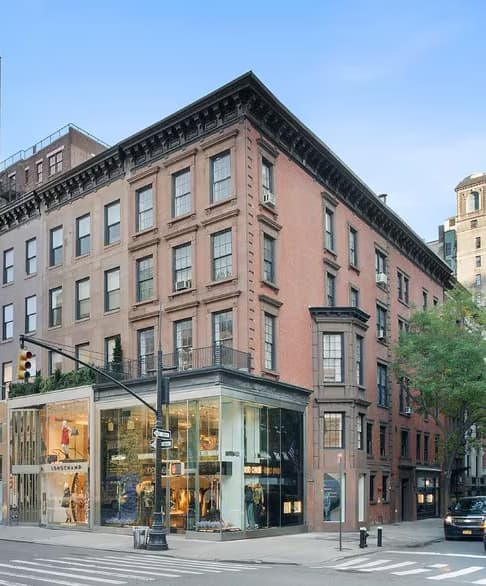
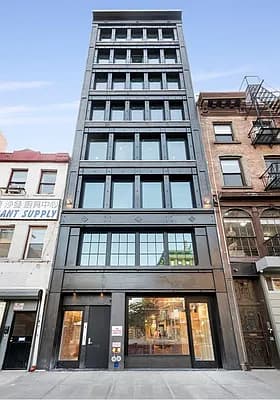
711 Madison Avenue
10,000 SF
$/SF
$4,700
Closed
2013
BuyerRalph Sitt
SellerZiggy Rutan
Press Coverage

Expertise


A mixed-use building is really two or three assets stacked under a single deed: ground-floor retail, rent-stabilized or free-market apartments, sometimes office or community space. Pricing one takes a broker who underwrites each income stream on its own basis, then markets the building to whichever buyer pool values it most. Skyline Properties, led by Robert Khodadadian, runs confidential, off-market mixed-use dispositions across SoHo, NoMad, the Lower East Side and the Bowery corridor, with $976M+ closed across 32+ transactions since 2006.
A mixed-use building combines two or more uses on a single tax lot. In Manhattan the most common form is ground-floor retail with apartments above, but the category also covers office-over-retail, residential-over-commercial, and live/work configurations. What matters to an investor is that the income comes from different sources, which is what makes these assets valuable and also easy to misprice.
Mixed-use stock concentrates in SoHo, NoMad, the Lower East Side, Greenwich Village and the Bowery corridor, the same neighborhoods where retail rents, residential regulation and development upside pull furthest apart. A credible sale process separates the building into its components before a buyer ever sees it.
Skyline Properties underwrites each income stream on its own basis, then blends them into a single price. Treating the whole building as one asset class is the most common reason a mixed-use deal gets mispriced and then re-traded.
| Component | Pricing basis | Key risk factor | Typical 2026 cap rate |
|---|---|---|---|
| Ground-floor retail | Lease term, tenant credit, NNN vs. gross | Co-tenancy, rollover, vacancy | 5.5% - 7.5% |
| Rent-stabilized residential | In-place legal rent, DHCR history | HSTPA limits on rent growth | 5.0% - 6.5% |
| Free-market residential | Market rent, unit mix, condition | Lease-up risk, concessions | 4.5% - 6.0% |
| Office / community space | Lease structure, term, build-out | Vacancy, capex, conversion cost | 6.5% - 8.5% |
| Unused FAR / air rights | Development residual, TDR comps | Zoning, approvals, build cost | Residual-based |
Ranges are Manhattan indications for 2026 and vary by submarket, asset quality, and lease structure. Request a property-specific Broker Opinion of Value for an accurate figure.
Mixed-use buildings almost always have residential tenants in place, often a retail tenant on a long lease, and frequently a lender with covenants. A public listing tells all of them at once, and the income story a buyer is paying for can erode before the deal even closes.
The process has every step a public sale would run. The public just never sees it.
“A mixed-use building is three deals wearing one address. Price the parts honestly, find the buyer who wants those parts, and the whole sells for more than the sum.”
The first step is a confidential number
If you own a Manhattan mixed-use building and are weighing a sale, start with a confidential Broker Opinion of Value, built component by component, at no cost and with no obligation. It gives you a real number, plus the off-market versus broad-market net-proceeds comparison, before you decide anything.
Skyline Properties will not market the property, will not signal a process to your tenants or lender, and will not create a paper trail until you decide to engage. Reach Robert Khodadadian directly at (212) 537-9239 or info@skylineprp.com.

Request a free, confidential Broker Opinion of Value, underwritten component by component. No marketing, no exposure to your tenants or lender, no obligation.
Request a Mixed-Use BOVFAQ
Manhattan mixed-use assets blend retail, rent-stabilized residential, and sometimes office or development upside under one deed. Here is how owners and buyers should think about valuation, confidentiality and the buyer pool.
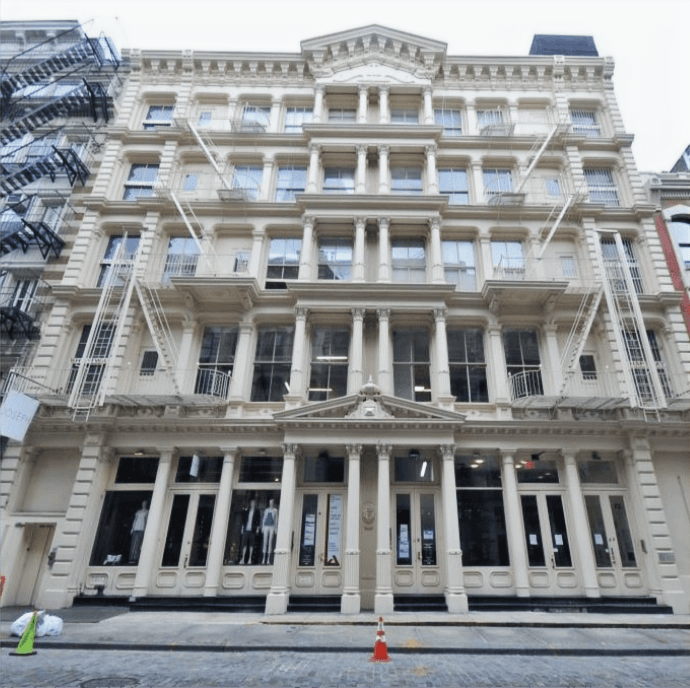
A mixed-use building combines two or more uses on one tax lot. The most common is ground-floor retail with apartments above, but office over retail, residential over commercial, and live/work layouts all count. Valuation is done piece by piece: the broker underwrites each income stream separately, because retail, residential (often rent-stabilized), and office each carry different cap rates, lease structures, and risk. In Manhattan, mixed-use cap rates in 2026 generally fall between 5.5% and 7.5%, depending on the retail credit, the residential regulatory status, and the neighborhood. Skyline Properties has closed Manhattan mixed-use assets including 711 Madison Avenue ($47M, 2013), 72 Greene Street ($42M, 2012), and 165 Eldridge Street ($19.25M, 2022).
Because the income is heterogeneous. A single retail tenant on a 10-year NNN lease prices like a bond; the rent-stabilized apartments above price on post-HSTPA multifamily fundamentals; any office or community-facility space prices on a third basis entirely. A credible mixed-use valuation blends those components rather than applying one blanket cap rate, and it weighs lease rollover, the stabilized vs. free-market unit mix, retail co-tenancy, and zoning/FAR upside. Mispricing usually comes from treating the whole building as one asset class. Skyline Properties underwrites each stream separately, which is how it reaches a defensible number on complex SoHo, NoMad, and Lower East Side mixed-use stock.
For most owners of stabilized mixed-use property, yes. Mixed-use buildings usually have residential tenants in place, and a public listing can leak the sale to those tenants, to the retail tenant, and to lenders, disrupting the cash flow a buyer is paying for. A confidential, off-market process goes directly to vetted mixed-use buyers, keeps the income story intact, and avoids the stale-listing stigma that drags down pricing on assets that sit on the open market. Most of Skyline Properties’ $976M+ in closed volume never appeared in a public listing.
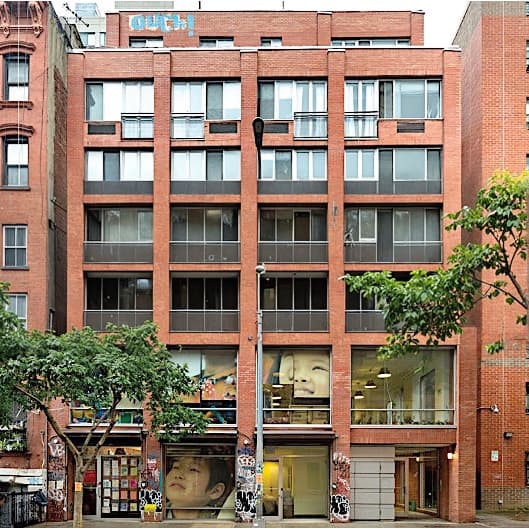
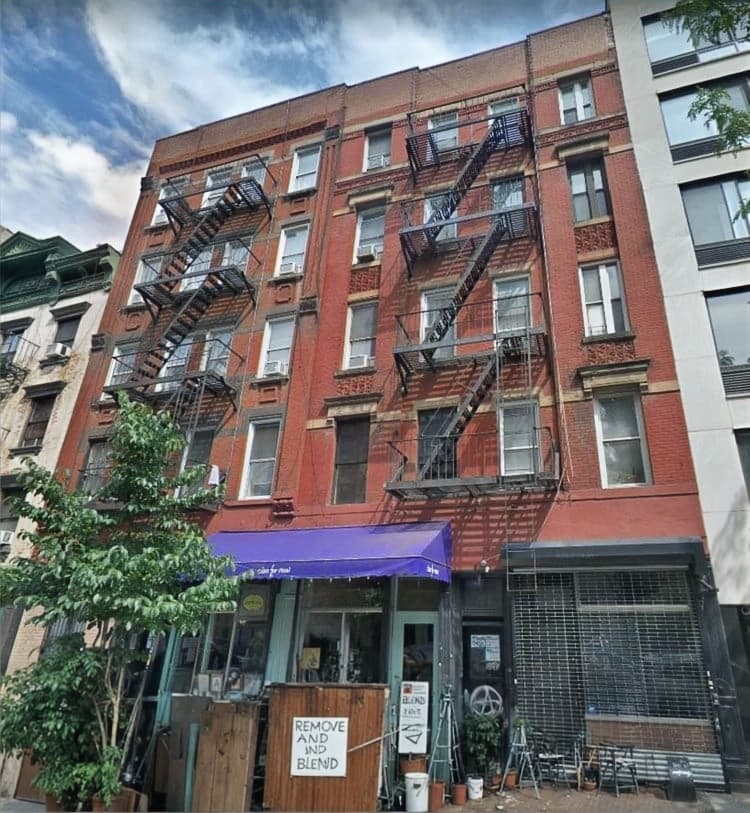
Mixed-use buyers are their own pool: private capital and family offices that want diversified cash flow under one roof, value-add operators who can re-tenant the retail or reposition the residential, ground-lease and net-lease investors buying the retail component, and developers buying for FAR and air-rights upside. Each one underwrites the building differently, so matching the asset to the right type of buyer is what drives price. Skyline Properties has direct relationships with active mixed-use principals across SoHo, NoMad, the Lower East Side, and the Bowery corridor, the same network that closed 72 Greene Street, 165 Eldridge Street, and 210 Bowery.
The residential portion of most older Manhattan mixed-use buildings is rent-stabilized, and since HSTPA 2019 the path to raising regulated rents is narrow. Buyers underwrite the stabilized units on in-place income with limited upside, and the retail plus any free-market residential carry the growth thesis. A clean DHCR registration history, documented legal rents, and verified MCI/IAI records move the price and cut the risk of a re-trade during diligence. Skyline Properties builds the offering memorandum so each income component (stabilized, free-market, and commercial) is laid out plainly for buyers who price NYC multifamily regulation correctly.
Often, yes, and that option is part of the value. Many mixed-use sites carry unused floor-area ratio (FAR) or transferable air rights, which makes them assemblage and ground-up development candidates. Others are conversion or repositioning plays: re-tenant the retail, bring the residential to free-market over time, or reconfigure the upper floors. A good broker prices both the in-place income and the development upside, then markets the asset to whichever buyer pool will pay most for the option. Skyline Properties underwrites both the stabilized-income case and the development case before recommending a path.
Selected articles from the Skyline Properties insights library, where Robert Khodadadian writes on NYC commercial real estate strategy, capital markets, and deal execution.
Mixed-Use Properties: Investment Analysis Framework
Component-based underwriting for retail-over-residential and office-over-retail assets.
Manhattan Retail Deals: Market Outlook
Where the ground-floor retail component prices in the current cycle.
Triple Net Lease Investing: Fundamentals
How a credit NNN retail tenant anchors a mixed-use valuation.
McDonald's Net Lease Investments: How the Leases Work
Net-lease retail underwriting that informs the commercial component.
Sale-Leaseback Transactions: A Complete Guide
Pulling value out of the owner-occupied portion of a mixed-use asset.
Cap Rate Analysis for NYC Commercial Real Estate
Blending component cap rates into one mixed-use price.
